Risk Heartbeat #04 — April 2026 issue
Risk Heartbeat April 2026 — commodity-financing dispersion graduates, second-order Financials contagion partially resolves, new payment-system signal.
Risk Heartbeat April 2026 — commodity-financing dispersion graduates, second-order Financials contagion partially resolves, new payment-system signal.
A free-tier sector risk lens — aggregate idiosyncratic risk, Risk Heartbeat coherence, sentiment compression, microstructure and regulatory signal by sector.
Two-tier AI agents — a cheap triage classifier in front of a deep LLM extractor. Cost, precision, and governance benefits, with the full design pattern.
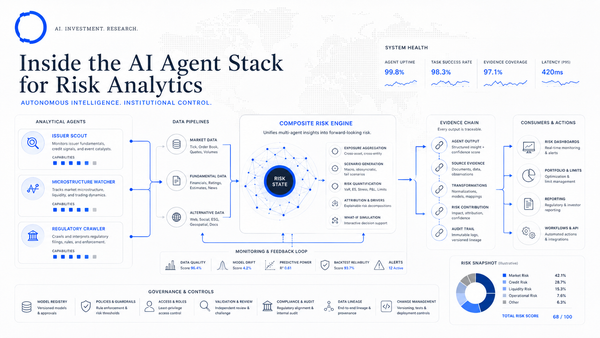
Technical walkthrough of Issuer Scout, Microstructure Watcher, Regulatory Crawler — the AI agent stack architecture behind Risk Heartbeat at DF Analytics.
Risk Heartbeat March 2026 — Financials signal priced in, commodity-financing dispersion graduates, EU AI Act clarifying note on agent documentation.
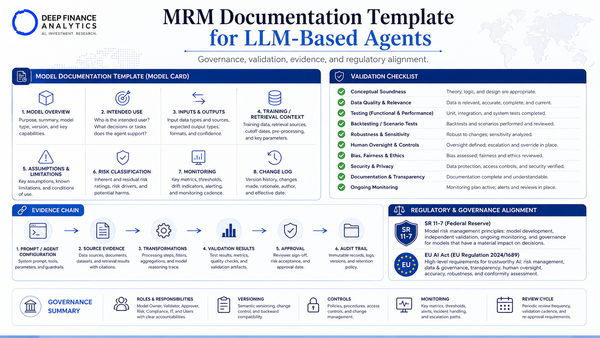
An 11-section MRM documentation template for LLM-based agents — practical, continuous, runtime-generated. Aligned with SR 11-7 and the EU AI Act.
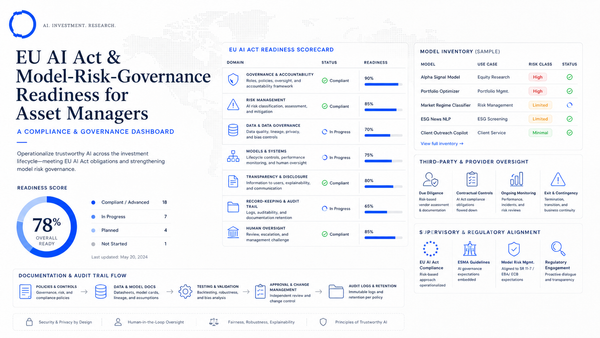
EU AI Act readiness checklist — 30 items across inventory, data, robustness, transparency, documentation, and vendor governance for asset managers in 2026.
ai governance financial services
Nine operational principles for AI governance in financial services — explainability, model registry, challenger models, drift monitoring, audit-readiness.
risk heartbeat february 2026
Welcome to issue #02 of Risk Heartbeat. February is a short month and a busy one — three of the four signals we covered in January moved meaningfully, and one materially new signal entered our watchlist. The format is the same as last month: what changed, three flagged signals, one macro
factor models institutional risk"
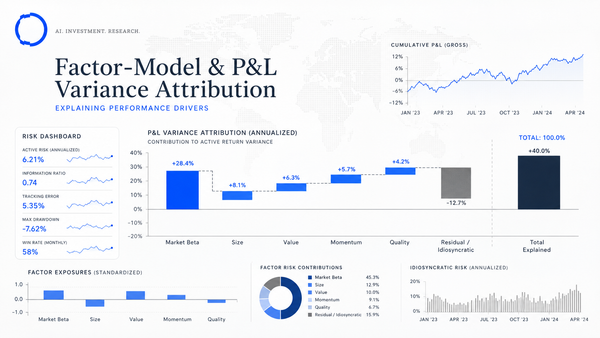
Where factor models still earn their place in 2026 and where they hide risk — residual concentration, stale loadings, non-stationary premia, and the fix.
idiosyncratic risk scoring
Epsilon scores idiosyncratic risk for every issuer in the investable universe, daily, using two-of-three coherence across price, narrative, and microstructure.
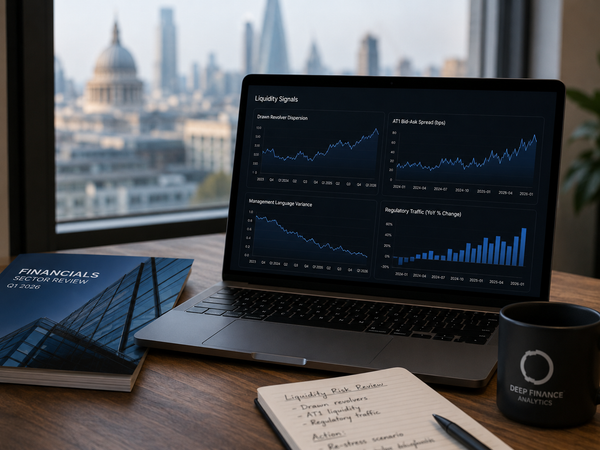
inancials liquidity stress signatures
Aspects Q1 2026 — four early-warning Financials liquidity stress signatures, the issuer clusters they identify, and the portfolio implications.